What FIRPTA withholding is
When a foreign person sells a U.S. real property interest, the buyer (the transferee) is generally the withholding agent and must withhold a percentage of the amount realized. If the buyer fails to withhold, the buyer may be liable for the tax.IRS
The withholding is a payment on account, not the final bill. The seller reports the sale on a U.S. return and attaches the stamped Form 8288-A to get credit for what was withheld.IRS Our FIRPTA refund service and refund guide cover that step.
When FIRPTA withholding is not required
The IRS lists these situations. Notification requirements still have to be met.IRS
- The buyer is an individual who will use the property as a home, and the sale price is not more than $300,000. The buyer or a family member must have definite plans to live there for at least 50% of the days it is used in each of the first two 12-month periods.
- The property is an interest in a domestic corporation whose stock is regularly traded on an established securities market.
- The corporation certifies, under penalties of perjury, that the interest is not a U.S. real property interest (dated not more than 30 days before transfer).
- The seller gives the buyer a certification, under penalties of perjury, that the seller is not a foreign person, with name, U.S. taxpayer ID and home address.
- The buyer receives a withholding certificate from the IRS that excuses withholding.
- The seller gives written notice of non-recognition of gain or loss under a Code or treaty provision.
- The amount the seller realizes is zero.
- The property is acquired by the U.S., a U.S. state or possession, a political subdivision or the District of Columbia.
The list also covers grants or lapses of options and interests in publicly traded partnerships or trusts.IRS Whether one fits your sale depends on the facts. The closing agent or buyer decides whether to withhold, so raise it early.
Withholding certificates: how to reduce or remove it
If no exception applies, the buyer, the buyer's agent or the seller can ask the IRS for a withholding certificate. The IRS may issue one because the amount to withhold would exceed the seller's maximum tax liability, because all the gain is exempt from U.S. tax, or because the parties made an agreement with the IRS to pay the tax with security.IRS
- Timing: the IRS generally acts within 90 days of a complete application with the TINs of all the parties.IRS
- Notice: a seller who applies must tell the buyer in writing, on the day of or the day before the transfer, that a certificate has been applied for.IRS
- Which form: Form 8288-B for the first three categories (nonrecognition or exemption, maximum tax liability calculation, and special installment sales). The other categories follow a format set out by the IRS.IRS
- A TIN is required. A foreign individual without an SSN can apply for an ITIN by attaching Form 8288-B to Form W-7.IRS
Our guide to the Form 8288-B withholding certificate goes through the application.
Forms 8288, 8288-A and 8288-B
| Form | What it is | Who files it |
|---|---|---|
| Form 8288 | U.S. withholding tax return for dispositions by foreign persons. It reports and pays the tax withheld. | The buyer, generally by the 20th day after the transfer.IRS |
| Form 8288-A | Statement of withholding. The IRS stamps copy B and sends it to the seller. | The buyer prepares it for each seller. The seller attaches the stamped copy to their U.S. return.IRS |
| Form 8288-B | Application for a withholding certificate to reduce or eliminate withholding. | The buyer, the buyer's agent or the seller.IRSIRS |
If the seller's TIN is missing from Form 8288-A, the IRS will not forward a stamped copy B. It mails the seller a letter telling them to apply for an ITIN with Form W-7.IRS Sellers who need one can read about our ITIN service.
Your questions answered
A situation where the buyer does not have to withhold, such as a home purchase of $300,000 or less, a seller who certifies they are not a foreign person, or an IRS withholding certificate.IRS
An IRS certificate that reduces or eliminates the amount the buyer must withhold. It can be issued because the withholding would exceed the seller's maximum tax liability, the gain is exempt, or there is an agreement to pay the tax with security.IRS
The IRS generally acts on a complete application within 90 days of receiving it.IRS
A certification the seller gives the buyer, under penalties of perjury, that the seller is not a foreign person. It includes the seller's name, U.S. taxpayer ID and home address.IRS
You need a U.S. taxpayer ID to apply for a certificate and to get credit for withholding. A foreign individual without an SSN can apply for an ITIN, and the IRS lets a seller apply under Exception 4.IRS
More questions? See the full Nolly.com FAQ.
How we checked this
Every IRS fact on this page comes from IRS.gov or the other official pages listed below and was checked on October 2, 2026. Nolly.com's own prices are the only exception. Nolly.com is a private company and is not part of the IRS.
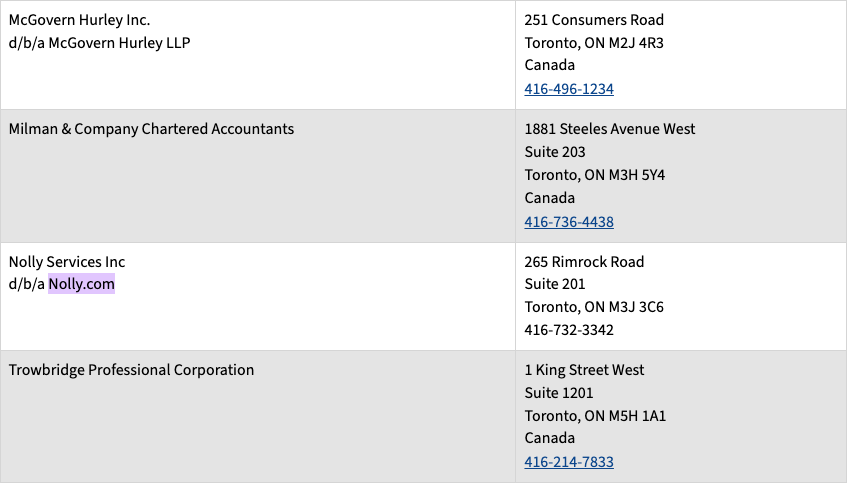
Nolly Services Inc, d/b/a Nolly.com, appears on the IRS page Acceptance agents – Canada. Nolly.com is a private company and isn't part of the IRS.
- FIRPTA withholdinghttps://www.irs.gov/individuals/international-taxpayers/firpta-withholding
- Exceptions from FIRPTA withholdinghttps://www.irs.gov/individuals/international-taxpayers/exceptions-from-firpta-withholding
- Reporting and paying tax on U.S. real property interestshttps://www.irs.gov/individuals/international-taxpayers/reporting-and-paying-tax-on-us-real-property-interests
- Withholding certificateshttps://www.irs.gov/individuals/international-taxpayers/withholding-certificates
- Applications for FIRPTA withholding certificateshttps://www.irs.gov/individuals/international-taxpayers/format-for-applications
- ITIN guidance for foreign property buyers/sellershttps://www.irs.gov/individuals/international-taxpayers/itin-guidance-for-foreign-property-buyers-sellers
Checked against IRS.gov on October 2, 2026. General information, not tax advice.