What FIRPTA withholding is, and what it isn't
FIRPTA is the Foreign Investment in Real Property Tax Act. When a foreign person sells a U.S. real property interest, the buyer must withhold 15% of the amount realized and send it to the IRS.IRS
Three details matter more than they look.
- It's the buyer's job, and the buyer is on the hook. In most cases the buyer is the withholding agent. If the seller is a foreign person and the buyer doesn't withhold, the buyer may be held liable for the tax.IRS That is why closing agents withhold even when a seller objects.
- The 15% is on the amount realized, not your profit. The amount realized is the cash paid or to be paid, the fair market value of other property transferred, and any liability the buyer assumes.IRS
- It's a prepayment, not the final tax. Gain on U.S. real property is taxed as if you were in a U.S. business, on a Form 1040-NR. You claim the tax withheld as a payment on that return.Pub. 519
Deep diveWhat counts as a U.S. real property interest
Land and buildings in the U.S. or the U.S. Virgin Islands, mines and wells, and associated personal property such as farming machinery all count. So does an interest, other than as a creditor, in a domestic corporation that was a U.S. real property holding corporation during the look-back period.IRS
A holding corporation is one whose U.S. real property is at least 50% of the value of its real property interests and trade or business assets.Pub. 519
If a property is owned by a foreign person and one or more others, the amount realized is allocated by capital contribution, and spouses are treated as contributing 50% each. A U.S. spouse can't take 100% of the proceeds to avoid withholding on the foreign spouse's share.IRS
From withholding to refund: three steps
Withholding is settled on your U.S. return. The sequence is the same for every seller.
15% is withheld
The buyer withholds tax from the sale price and sends it to the IRS, with Form 8288, within 20 days.IRS
Form 8288You get proof of it
The IRS stamps Copy B of Form 8288-A and forwards it to you at the address on the form. It is your credit.IRS
Form 8288-AWe file your return
We report the sale on your non-resident return and claim the withholding. If more was withheld than you owe, the IRS refunds the difference.
Form 1040-NRYou can't stop the buyer withholding, but two things are yours. One is whether your taxpayer number is on Form 8288-A, because without it the IRS doesn't stamp or send Copy B.IRS The other is whether you file: the IRS says the seller must file a U.S. return and attach the stamped form to receive credit for the tax withheld.IRS
Withholding versus your gain
Withholding is on the full sale price. Tax is on your gain: the sale price less what you paid and your costs. Move the sliders to see the gap.
Illustration only, not tax advice. Lower withholding can apply when the buyer will live in the home: 10% at $1,000,000 or less, none at $300,000 or less.IRS Your tax depends on your gain after costs and depreciation, and on your situation.
If the property was your home, check the home-sale exclusion. The IRS says it may apply to non-resident aliens who meet the eligibility test, up to $250,000 on a separate Form 1040-NR. When it applies, the statutory withholding can exceed your maximum tax, and you can ask the IRS for a withholding certificate.IRS
FIRPTA withholding rates at a glance
The standard rate is 15%. A few situations change it.
| Situation | Withholding | What has to happen |
|---|---|---|
| Standard sale by a foreign person | 15% of the amount realized | The buyer withholds and files Forms 8288 and 8288-A by the 20th day after transfer IRS |
| Buyer will live there, price over $300,000 up to $1,000,000 | 10% | The buyer or family has definite plans to live there at least 50% of the days it is used, in each of the first two 12-month periods IRS |
| Buyer will live there, price $300,000 or less | None | Same residence test. The buyer must be an individual, and notice requirements apply IRS |
| Seller certifies not a foreign person | None | A certification under penalties of perjury with name, taxpayer ID and home address IRS |
| IRS withholding certificate | Reduced or none | Form 8288-B, normally decided within 90 days of a complete application IRS |
The residence exception depends on what the buyer plans, not on you. The IRS suggests making sure the buyer and the closing agent both know about it before closing.IRS
How to get your FIRPTA money back, step by step
Six steps, in order. You can do them yourself, or have us file for you.
- 1
Get a U.S. taxpayer number
You need an SSN or an ITIN to claim the credit. If you aren't eligible for an SSN, apply for an ITIN with Form W-7 under Exception 4, once there is a binding sale contract.IRS Your number has to be on Form 8288-A, or the IRS can't stamp your copy.IRS Our ITIN overview explains the form.
Form W-7, Exception 4 - 2
Check the buyer's filings
The buyer files Form 8288 and Form 8288-A by the 20th day after the transfer.IRS Make sure your name, taxpayer number and the amount withheld are right. If your number is missing, the IRS processes the forms without stamping Copy B and sends you Letter 3794 asking you to apply for an ITIN.IRS
Form 8288-A - 3
Receive the stamped Form 8288-A
The IRS stamps Copy B and forwards it to you at the address on the form.IRS Keep it with your closing statement. If no stamped copy can be issued because your number was missing, you attach substantial evidence of the withholding instead, such as closing documents, plus a statement with the details from Forms 8288 and 8288-A including your number.IRS
Copy B, IRS-stamped - 4
Work out your gain
Your gain is the amount realized less your adjusted basis. The IRS asks to see evidence of basis such as closing statements, improvement invoices and depreciation schedules.IRS If the property was your home, check the home-sale exclusion, up to $250,000 for a non-resident filing separately.IRS
Basis and costs - 5
File Form 1040-NR for the year of the sale
Report the sale, enter the tax withheld on the line for Form 8288-A (line 25f on the 2025 form), and attach Form 8288-A to the front of the return.IRS With no U.S. wages, the return is due the 15th day of the 6th month after the tax year ends: June 15, 2026 for a 2025 sale.IRS Report the sale in the year it actually closed, even if the date on Form 8288-A is later.IRS
Form 1040-NR - 6
Refund claims have time limits. For an amended return, the IRS generally allows 3 years from the date you filed the original or 2 years from the date you paid the tax, whichever is later.Pub. 519 A late first return has its own limits, so ask before you assume it is too late.
Reduce the withholding first: Form 8288-B
A withholding certificate asks the IRS to approve a lower amount, or none, before the buyer sends money in. Either the buyer or the seller can apply with Form 8288-B.IRS The IRS can issue one when the amount to be withheld would exceed your maximum tax liability, when all of your gain is exempt from U.S. tax, or under an agreement to pay the tax with security.IRS
Selling soon? Apply on or before the transfer date.
Tell the buyer in writing that you applied, on or before the day of transfer. If the application is still pending at closing, the buyer withholds the full amount but doesn't pay it to the IRS until the 20th day after the IRS mails the certificate or a denial.IRS
While the IRS decides, the buyer can hold the 15% in escrow until 20 days after the IRS's final determination.IRS A certificate issued after the transfer may authorize an early refund or a normal one.IRS
| Route | When | What happens | IRS timing |
|---|---|---|---|
| Claim on your return | After closing, on Form 1040-NR | Full 15% is withheld. The IRS refunds any excess | Allow up to 6 months IRS |
| Certificate before closing | Apply on or before the transfer date | The buyer withholds less, or nothing | Normally 90 days IRS |
| Certificate after closing | After the transfer | May authorize an early refund or a normal one IRS | Early refund request by letter or Form 843 IRS |
Deep diveWhat a Form 8288-B application includes
Every party's taxpayer ID must be on the application. If you need an ITIN, you attach the completed Form 8288-B to Form W-7 and send both to the IRS.IRS
For a maximum-tax claim you attach a calculation: the signed sale contract, evidence of adjusted basis such as closing statements, improvement invoices and depreciation schedules, any depreciation to be recaptured, the maximum tax rates, the tentative tax, and any treaty reduction. You also sign a statement under penalties of perjury.IRS
Our Form 8288-B guide walks through an application, and our withholding rate explainer covers when reduced rates fit.
FIRPTA and Canada: selling a Florida or Arizona condo
Many Canadian snowbirds sell a winter home sooner or later. FIRPTA applies to them like any foreign seller, so 15% is usually withheld at closing, and a Form 1040-NR settles it afterwards.IRS
You need a U.S. taxpayer number to claim the credit. A Canadian SIN isn't one, so a Canadian seller without an SSN applies for an ITIN. Our guide to getting an ITIN from Canada covers how, and the IRS lets a seller apply once there is a binding sale contract.IRS
You also report the sale at home. If your Canadian return includes foreign income that was taxed in the U.S., you may claim the federal foreign tax credit on Form T2209: the lesser of the foreign tax you paid and the Canadian tax payable on that income. Foreign amounts are converted to Canadian dollars at the Bank of Canada rate on the day they arose.CRA This guide covers the U.S. side. A cross-border tax professional can show how the sale and the credit fit together.
How long does a FIRPTA refund take?
There is no single IRS number for the whole journey, because it runs in stages. The IRS gives a figure for most of them.
Illustration of the stages. Only the figures that carry a source link are IRS ranges. Not a guarantee.
Two other clocks can run first. A withholding certificate takes about 90 days from a complete application. An ITIN takes 7 weeks, or 9 to 11 if you apply from abroad.IRS The IRS FIRPTA FAQ also says an ITIN requested together with a withholding certificate application is processed within 10 days of receipt.IRS
Add the stages together and the answer can run to months. Our guide to how long a FIRPTA refund takes walks through the order. Nobody can promise the IRS's pace.
Mistakes that hold up a FIRPTA refund
- No taxpayer number on Form 8288-A. The IRS then processes the forms without stamping Copy B, and writes to you asking you to apply for an ITIN.IRS
- Treating the withholding as the final tax. It doesn't settle anything on its own. You get credit by filing a return and attaching the stamped form.IRS
- Applying for a certificate too late. The application has to reach the IRS on or before the transfer date, and the buyer needs written notice.IRS
- Reporting the sale in the wrong year. Report it in the year it actually closed, even when a certificate request moves the date shown on Form 8288-A.IRS
- Missing basis records. Both a maximum-tax calculation and your return rest on adjusted basis: closing statements, improvement invoices and depreciation schedules.IRS
- Asking for an ITIN too early. With no other valid reason, the IRS will deny an ITIN requested before you have a binding contract to sell.IRS
What Nolly.com charges
A fixed price in U.S. dollars, confirmed before we start. See all Nolly.com prices.
- Form 1040-NR reporting your sale
- Withholding credit claimed with Form 8288-A
- Updates until the IRS processes it
- Filed together with your return
- Identity verified on a video call with a Certifying Acceptance Agent
- See how ITIN identity checks work
Prices in U.S. dollars.
FIRPTA withholding refund: your questions answered
The buyer withholds it from the price and sends it to the IRS, so it comes out of the seller's proceeds. The buyer is the withholding agent and may be held liable if they don't withhold.IRS
No. It is a prepayment of 15% of the amount realized, not of your gain. Your tax is worked out on your U.S. return, and the withholding is credited against it.Pub. 519
It is the application for a withholding certificate that reduces or removes FIRPTA withholding. The buyer or the seller can file it, on or before the transfer date, and the IRS normally acts within 90 days of a complete application.IRS
The IRS processes the forms but doesn't stamp Copy B, and writes to you to apply for an ITIN. You can still claim credit by attaching closing documents and a statement with the details from Forms 8288 and 8288-A, including your number.IRS
Yes. FIRPTA applies to any foreign person. A Canadian selling a Florida or Arizona condo usually has 15% withheld and files Form 1040-NR to settle it.IRS Canadian reporting is separate, and the foreign tax credit may help.CRA See our guide to getting an ITIN from Canada.
Sometimes. Withholding isn't required if the buyer will live there and the price is $300,000 or less, if you certify you aren't a foreign person, or if the IRS issues a withholding certificate.IRS
The home-sale exclusion can apply to non-resident aliens who meet the eligibility test, up to $250,000 on a separate Form 1040-NR. If it applies, withholding can exceed your tax, and you can ask the IRS for a withholding certificate.IRS
The buyer may be liable for the tax, plus penalties and interest.IRS You still need to report the sale and pay any tax on your gain. Don't skip the return because nothing was withheld.
More questions? See the full Nolly.com FAQ.
How we checked this
Every figure on this page comes from IRS.gov or the Canada Revenue Agency and was checked on October 1, 2026. Nolly.com's own prices are the only exception.
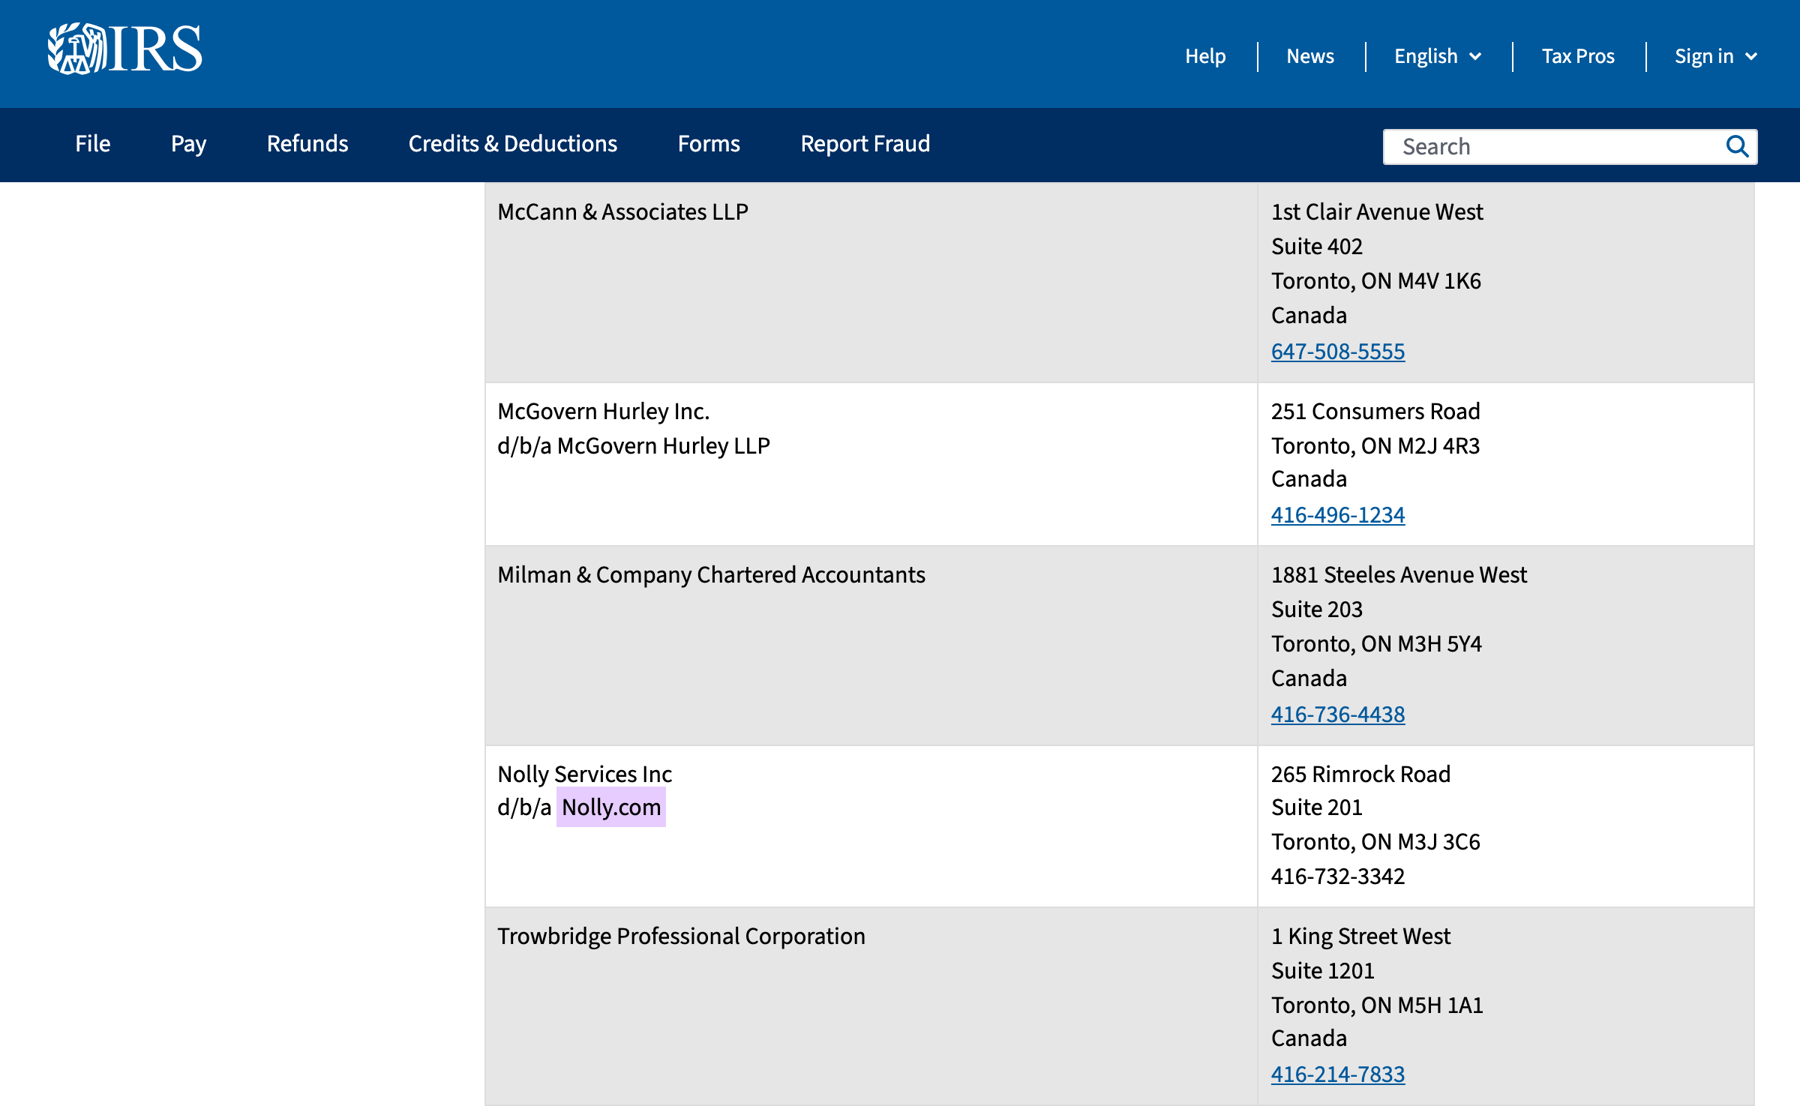
Nolly Services Inc, d/b/a Nolly.com, appears on the IRS page Acceptance agents – Canada. Nolly.com is a private company and isn't part of the IRS.
- Instructions for Form W-7 (Rev. 12-2024)https://www.irs.gov/instructions/iw7
- Acceptance agents - Canada (IRS list; page reviewed 30 September 2026)https://www.irs.gov/individuals/international-taxpayers/acceptance-agents-canada
- Publication 519, U.S. Tax Guide for Alienshttps://www.irs.gov/publications/p519
- Canada Revenue Agency: Federal foreign tax credit (line 40500)https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/about-your-tax-return/tax-return/completing-a-tax-return/deductions-credits-expenses/line-40500-federal-foreign-tax-credit.html
- Instructions for Form 1040-NR (2025)https://www.irs.gov/instructions/i1040nr
- FIRPTA withholdinghttps://www.irs.gov/individuals/international-taxpayers/firpta-withholding
- Exceptions from FIRPTA withholdinghttps://www.irs.gov/individuals/international-taxpayers/exceptions-from-firpta-withholding
- Reporting and paying tax on U.S. real property interestshttps://www.irs.gov/individuals/international-taxpayers/reporting-and-paying-tax-on-us-real-property-interests
- Withholding certificateshttps://www.irs.gov/individuals/international-taxpayers/withholding-certificates
- ITIN guidance for foreign property buyers/sellershttps://www.irs.gov/individuals/international-taxpayers/itin-guidance-for-foreign-property-buyers-sellers
- Instructions for Form 8288 and Form 8288-Ahttps://www.irs.gov/instructions/i8288
- Form 8288-B and instructions (Rev. 12-2025)https://www.irs.gov/pub/irs-pdf/f8288b.pdf
- Internal Revenue Manual 21.8.5, FIRPTA related issueshttps://www.irs.gov/irm/part21/irm_21-008-005r
Reviewed by Nolly.com's Certifying Acceptance Agent team. Updated October 1, 2026. General information, not tax advice.