Two withholding payments and two tax authorities
California calls real-estate withholding a prepayment of income tax on the sale. It can cover land, buildings, homes and other real-property interests.California FTB Federal FIRPTA is a different payment to the IRS, so one withholding record cannot prove both amounts.
Make two folders: California Form 593 and the FTB payment records in one, federal Forms 8288 and 8288-A in the other. Compare each seller’s legal name and tax number across both. Ask escrow to correct an error before treating a closing-statement total as a credit.
If a trust holds title, state records depend on whether it is a grantor or nongrantor trust. The FTB explains when grantor details or the trust’s name and EIN are used.California FTB Give the preparer the trust documents rather than entering the trustee’s personal details by default.
Complete Form 593 before escrow closes
Form 593 can certify a full or partial exemption, estimate a loss or zero gain, calculate an alternative withholding amount and report withholding. For a 2026 closing, use the 2026 instructions.California FTB An exemption claim needs to reach escrow before the transaction closes.
The sales-price method is 3 1/3% of the relevant sales-price amount. An alternative calculation uses estimated gain and the applicable tax rate. Those are California methods, not substitutions for federal FIRPTA.California FTB Ask escrow which method the completed form uses.
Bring the original purchase statement and improvement records early if a gain-based calculation is being considered. Estimate the tax history with your preparer rather than selecting a lower withholding option without supporting figures.
A California exemption is not the end of the filing
The FTB says an exemption from withholding does not remove the obligation to file a California return and pay tax due. After closing, withheld amounts are recovered by claiming the credit on the appropriate year’s return.California FTB
Ask your preparer which California return applies to your residency and ownership. If you are an individual nonresident, the state return review belongs alongside the federal nonresident return. Agree the scope of both before paying for preparation.
Keep the amount in Form 593 line 37 with the state filing records. If an installment payment or failed exchange caused withholding in another year, flag that timing. Matching the credit to the correct year is a separate task from reporting the original sale.California FTB
Check each owner and the transaction type
The FTB normally requires a separate Form 593 for each seller. Married couples or registered domestic partners planning a joint return can share a form; unequal ownership interests can require separate forms to show the correct shares.California FTB Tell escrow about the actual ownership percentages.
Also identify installment sales, exchange proceeds and any failed exchange. The 2026 form has fields for those different transactions.California FTB Keep the promissory note or exchange paperwork so your preparer can trace how and when money was received.
A California withholding exemption and a federal FIRPTA exemption must each be established under their own rules. Review the federal exceptions before asking escrow to omit the IRS payment.
How the federal FIRPTA refund is worked out
FIRPTA generally requires 15% withholding on the amount realized, with exceptions and reduced rates for certain sales.IRS The seller’s final federal tax is calculated on the return; withholding is a credit against that result.IRS A refund depends on the actual calculation and cannot be promised from the sale price alone.
A withholding certificate request on Form 8288-B is a separate process from a later refund return. If one was submitted, keep its date and the IRS response with the closing papers.IRS For an individual foreign seller, have the Form 1040-NR filing reviewed with the property history.
If an ITIN is needed, W-7 has a specific real-property exception and supporting-document rules.IRS Applying for the number alone does not claim your refund. Nolly.com’s FIRPTA refund service starts at US$499 and includes the ITIN application if you need one. Ask which state work is included in your quote.
Prepare your sale records in four steps
- 1
Review the seller and the closing
Confirm ownership, the sale date and which authority received each withholding payment.
Your transaction - 2
Collect the state records
Gather the state documents explained above alongside the signed purchase and sale statements.
Property file - 3
- 4
File and track each result
Prepare the federal return with withholding evidence, and review any separate state filing. Keep notices for each authority.IRS
After closing
Get help with your FIRPTA filing
Start with the whole property sale, including any state records. Nolly.com is an IRS-listed Certifying Acceptance Agent. If you need an ITIN, your interview is a live video call. No mailing your original passport to the IRS.
The IRS has typically taken about 9 to 11 weeks for ITIN applications lately. Timing depends on the IRS and your application; that is not a FIRPTA refund timeline. Refund processing and any state filing follow their own process.
FIRPTA refund
Claim back tax withheld when you sold U.S. property.
Includes:
- Closing statement and Form 8288-A reviewed
- Form 1040-NR prepared to claim the refund
- Filed with the IRS
- Status updates
- ITIN application included, if you need one
Your questions answered
No. Form 593 reports California withholding; Form 8288-A is federal. Keep both and claim each credit through the relevant filing.California FTBIRS
That is the sales-price method. Exemptions and an alternative gain calculation can apply under Form 593 rules.California FTB
No. FTB explicitly separates withholding exemptions from the duty to file and pay tax due.California FTB
The FTB says amounts withheld after closing are recovered through the credit on the appropriate year’s state return. Have errors in the underlying form reviewed too.California FTB
FIRPTA refund help starts at US$499 and includes the ITIN application if needed. Ask for the scope and price of any state filing before paying.
Only if the final tax and withholding credit produce that result. Withholding is not a guaranteed refund.IRS
More questions? See the full Nolly.com FAQ.
How we checked this
Every IRS fact on this page comes from IRS.gov or the other official pages listed below and was checked on October 3, 2026. Nolly.com's own prices are the only exception. Nolly.com is a private company and is not part of the IRS.
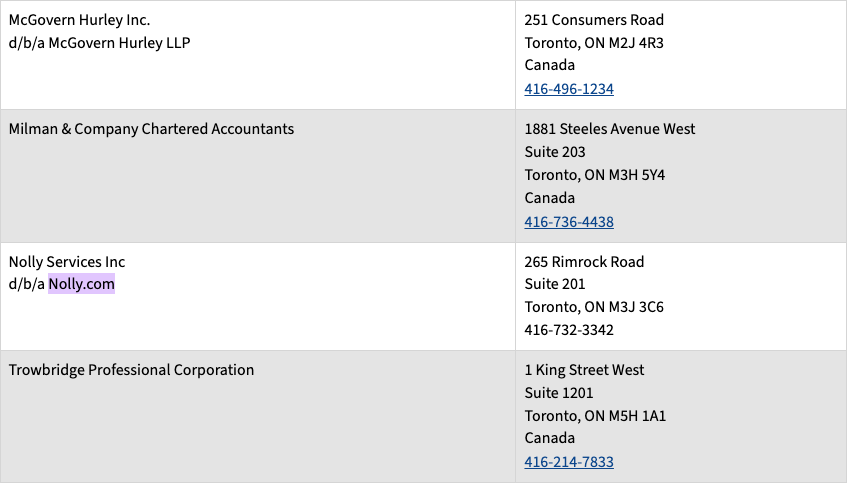
Nolly Services Inc, d/b/a Nolly.com, appears on the IRS page Acceptance agents – Canada. Nolly.com is a private company and isn't part of the IRS.
- Instructions for Form W-7 (Rev. 12-2024)https://www.irs.gov/instructions/iw7
- FIRPTA withholdinghttps://www.irs.gov/individuals/international-taxpayers/firpta-withholding
- Reporting and paying tax on U.S. real property interestshttps://www.irs.gov/individuals/international-taxpayers/reporting-and-paying-tax-on-us-real-property-interests
- Withholding certificateshttps://www.irs.gov/individuals/international-taxpayers/withholding-certificates
- ITIN guidance for foreign property buyers/sellershttps://www.irs.gov/individuals/international-taxpayers/itin-guidance-for-foreign-property-buyers-sellers
- 2026 instructions for Form 593https://www.ftb.ca.gov/forms/2026/2026-593-instructions.html
- California real estate withholdinghttps://www.ftb.ca.gov/pay/withholding/real-estate-withholding.html
Checked against IRS.gov on October 3, 2026. General information, not tax advice.